Saudi Arabia went looking for allies against Ansar Allah, and so far it has gotten statements of support. Egypt has declared its readiness to back the Kingdom, but its statement does not commit to any military involvement. Pakistan and Turkey have pledged troops under the Mecca Joint Defense Agreement signed in August, but both governments say their forces will play “a supportive rather than active combat role” against the Houthis. I have watched coalition pledges like these for decades. Cairo has not forgotten its war in Yemen in the 1960s. Islamabad has its own border with Afghanistan and a restless India to think about. Neither is going to send its soldiers into the mountains of Saada, so Riyadh will be fighting this one essentially alone.
That matters because Ansar Allah has shown it can reach the Kingdom’s economic core. In the past two weeks the Houthis have struck at Aramco facilities near Riyadh, the Shedgum gas plant in the Ghawar corridor, and the Tanajib oil facility on the Gulf coast. They hit an administrative building at Aramco’s Dhahran headquarters, the company’s historic nerve center. Now they are reportedly targeting Yanbu.
Riyadh says little about the damage, and Aramco’s chief executive insists the company’s system is intact and can be restored to its full 12 million barrels a day within days. I don’t believe it. Karl Miller, who is on the ground in the region, tells me the Saudis have suffered significant damage. That matches what we can see from the outside: a coalition that keeps announcing interceptions while fires keep burning at the targets. Repairing gas-processing trains, stabilization units and refinery components is not a matter of days. After the 2019 Abqaiq-Khurais strike, Saudi output fell by 5.7 million barrels a day, and it took about two months to recover from a single attack on an undefended site. This time the attacks are sustained and repeated, and the repair crews are working under fire.
Yanbu is the crucial target. With Iran’s navy declaring the Strait of Hormuz closed except to vessels it authorizes, Saudi Arabia’s Red Sea terminal at Yanbu, fed by the East-West Pipeline, is the Kingdom’s escape route to world markets. Flows through Hormuz fell to 11.62 million barrels a day in the week to October 13, against a baseline of 17.15 million. That bypass is already badly damaged. The East-West Pipeline is designed to carry up to 7 million barrels a day across the peninsula, pushed along by 11 pumping stations. According to my sources in the region, four of those 11 stations have been severely damaged and are not functioning. This did not come out of nowhere. In September, an attack damaged pumping facilities and knocked the pipeline largely out of service, and regional officials told the Associated Press repairs would take three to five weeks. Aramco got the line back up, and it has been hit again. A pipeline missing more than a third of its pumping stations cannot move anything close to its rated volume, however much crude is waiting in the Eastern Province.
Meanwhile Ansar Allah has seized Greater and Lesser Hanish islands and Perim inside the Bab al-Mandab, putting it astride the very sea lanes that tankers leaving Yanbu must use. Damaged production, a crippled pipeline and a contested Red Sea together mean the world loses Saudi barrels three times over: some cannot be produced, some cannot reach the coast, and what reaches the coast cannot be shipped safely.
Diesel is where this hits hardest. Diesel moves the trucks, tractors, trains and ships that carry everything else, and Europe is one of the world’s dominant diesel importers. The International Energy Agency’s October report is blunt. Middle Eastern fuel exports are below half of pre-war levels, and diesel markets “will remain tight well into 2027.” The IEA does not expect lost diesel stocks to be replenished before the second half of 2027. Diesel benchmarks topped $200 a barrel in September and remain nearly double the price of crude, which is itself around $108 for Brent, up more than 75 percent from a year ago. Ukrainian drones keep hitting Russian refineries and export terminals, so Europe’s other traditional source of middle distillates is also impaired.
So when people ask me when diesel supply returns to normal, my answer is not soon. The IEA’s timeline, which does not account for sustained damage to Saudi facilities, points to the second half of 2027 at the earliest. A real recovery is at least a year away, and probably longer.
Don’t expect the Trump-Putin diesel deal to change that. As I have argued before, the Russian barrels are a rounding error. Moscow has cleared 500,000 tons for export, roughly 3.7 million barrels, with no shipping timeline. Even if every tranche Trump announced is delivered, about 4.8 million tons in total, that comes to roughly 36 million barrels spread over months. The first 300,000 tons equals less than one day of American transport diesel demand, and the full program equals less than four. Measured against the world’s lost Middle Eastern distillate exports, it is negligible. It also depends on Russian refineries that Ukrainian drones continue to hit, and on sanctioned tankers to carry it. The deal may make for a good headline. It will not move the supply curve, and so it will not bring down the price of diesel.
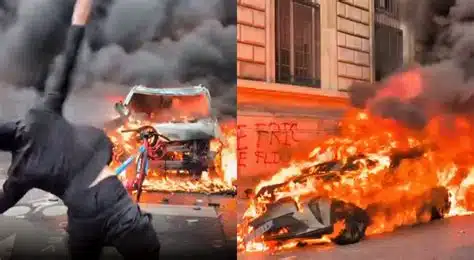
Europe is already paying the political price. On Saturday, France saw its worst rioting in years. The CGT union estimated more than 500,000 people in the streets protesting the cost of gasoline, energy and food, and more than 270 were arrested. In Milan, a demonstration against wars and rising living costs ended with barricades on fire and shops looted. Protests over the cost of living have spread to Belgium and Portugal. Albania has had five straight days of violent clashes in Tirana. The immediate trigger there is anger at Prime Minister Edi Rama, but it is part of the same continental mood of people who feel their governments have stopped listening.
This is the context in which Washington is considering new strikes on Iran. The ceasefire collapsed in July and has not been rebuilt. Every round of escalation since then has raised the price of oil, and each one has given Tehran a reason to tighten its grip on Hormuz and its allies in Yemen a reason to widen their target list. Another U.S. campaign will not reopen the Strait. It will further close it. It will push diesel prices back toward their September records just as Europe heads into winter, when heating oil demand peaks.
American policymakers seem to believe the costs of this war can be exported. They cannot. Europe’s economies were already weak before the war. Factories that run on diesel-powered logistics, farmers who need diesel for the harvest, and households that heat with fuel oil cannot absorb another price spike. The riots in Paris and Milan are a warning of what a long diesel shortage does to a society. If Washington widens this war, it will be choosing to make that shortage longer and deeper, and Europe will pay the bill on its streets.
Reprinted with permission from Sonar21.
